Ottawa Real Estate Market Update

In the fast-paced Ottawa real estate market, knowledge isn't just power—it's your strategic advantage. Understanding the latest trends in sales, pricing, and inventory is the first step toward making an empowered decision, whether you're planning to buy, sell, or invest. Here is our expert breakdown of the key data you need to know for.

RSS

OTTAWA REAL ESTATE-SEPTEMBER STATS (2026)

Ottawa Home Sales Hold Steady in September as New Listings Rise
Ottawa home sales held near August levels in September, edging slightly higher rather than declining as they typically do at this point in the year. At the same time, new listings rose much more sharply than usual, giving buyers greater choice and shifting market conditions further in their favour. 

Last month, weaker absorption was identified as one of the key signals to watch heading into the fall. That signal became more pronounced in September as the gap widened between the number of homes coming onto the market and the number selling. Whether that shift persists remains to be seen. New listings have declined in both October and November in each of the past 10 years, so the coming months will show whether September’s influx of listings recedes with the usual seasonal pattern or keeps inventory elevated for longer. 

The price picture was mixed. Average and median sale prices remained close to August and only slightly below last year, indicating that overall transactions did not change dramatically. The MLS® Home Price Index declined more noticeably, however, pointing to underlying price softness once changes in the mix of homes sold are taken into account.  

“Ottawa’s suburban areas remained the main engine of activity in the housing market, accounting for nearly three-quarters of all September sales and continuing to shape the citywide result,” said OREB President Tami Eades. “At the same time, the downtown and rural areas continue to see more volatility with a widening gap between the number of homes coming onto the market and the number selling.” 

Residential Market Activity 

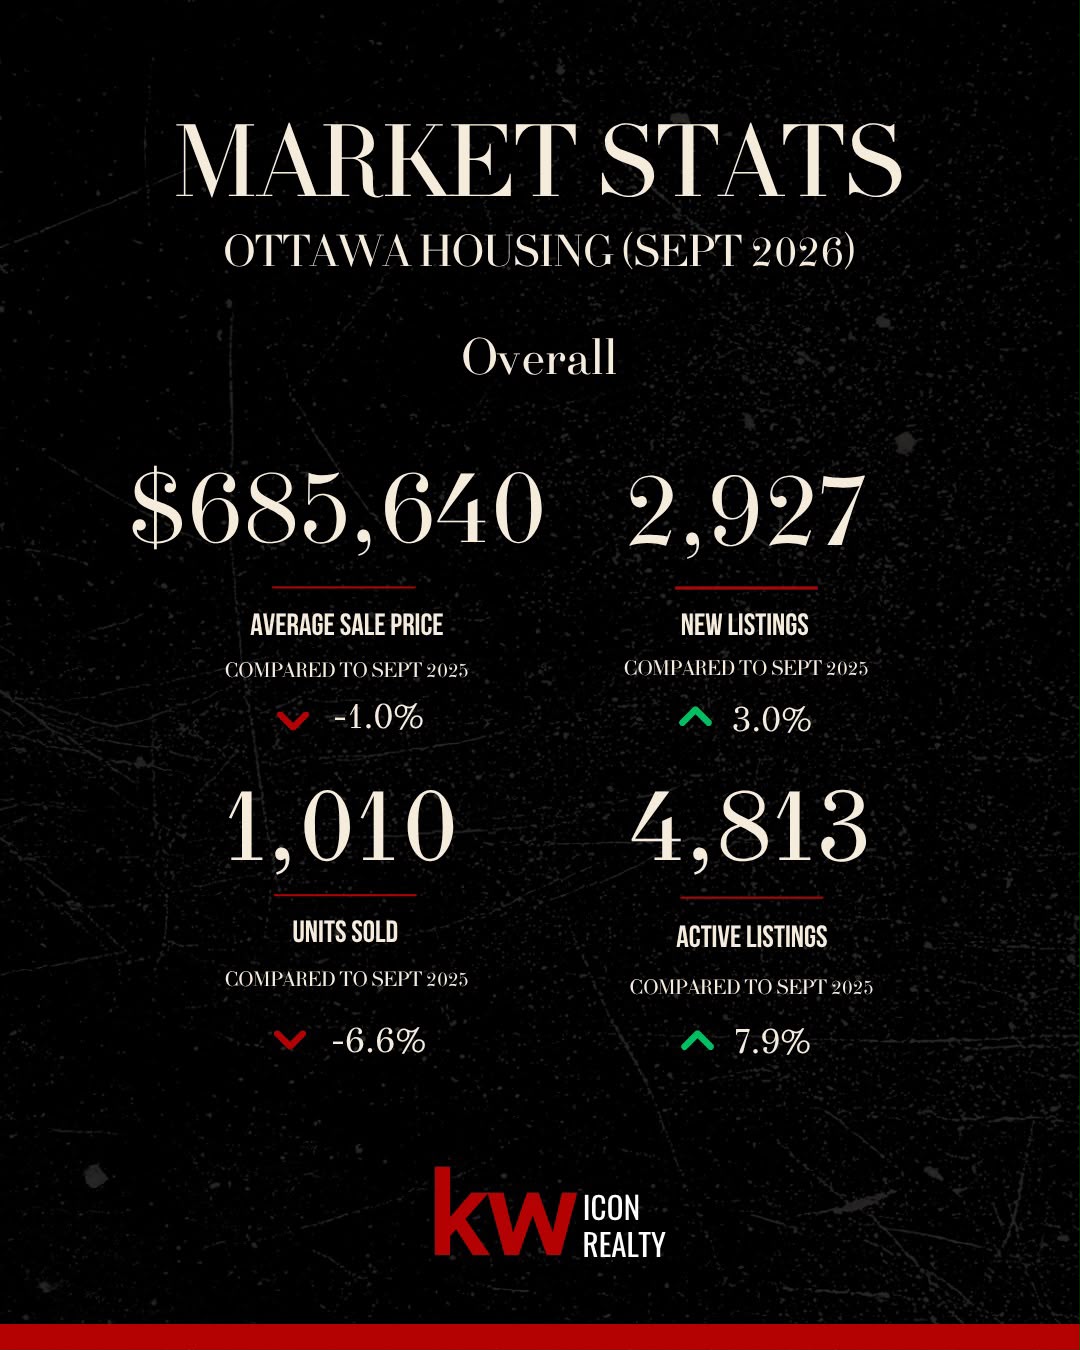
A total of 1,010 homes were sold through the MLS® System in September, down 6.6% from September 2025. Sales edged up 0.8% from August, when 1,002 transactions were recorded. Only one of the previous 10 August-to-September periods produced an increase in sales, while the median change was a decline of 5.9%. 

Looking across July through September provides a clearer view of the summer market. Sales typically ease gradually over these three months. In seven of the previous 10 years, activity declined in both August and September. This year followed a less even path, with an approximately 24% decline from July to August followed by September’s small increase.  

The three-month total was 3,336 sales, down 8.2% from the same period in 2025 and the third-lowest summer total since 2016. Taken together, the results point to a softer and unusually uneven summer, with September stabilizing after August rather than signaling a broader rebound. 

Sales were lower than a year earlier across all three major property types. Single-family sales declined 4.6% to 535 transactions, while townhouse sales fell 3.5% to 329. The largest decline remained in apartments, where sales fell 24.8% to 121 transactions. Apartments accounted for more than half of the net year-over-year decrease in citywide sales. 

Year to date, 10,288 homes have sold in Ottawa, down 6.9% from the same period in 2025. Total year-to-date dollar volume was approximately $7.2 billion, down 7.3%. 

Prices and Market Balance 

The average residential sale price was $685,640 in September, down 1.0% from a year earlier and nearly unchanged from August. The median sale price was $625,000, down 0.8% year over year and slightly higher than in August. Despite the volatility in sales activity, the average price remained within a range of less than 1% from July through September. 

The MLS® Home Price Index recorded a composite benchmark price of $623,500, down 0.3% from September 2025 and 2.2% from August. Average and median prices can be influenced by the types of homes sold in a given month. For example, a larger share of higher-priced sales or detached homes as opposed to condos can support the average even when home values are generally softening. The HPI reduces this effect by tracking the estimated price of a representative home with consistent characteristics. Its larger decline therefore points to more underlying price softness than the average and median figures alone suggest. 

September’s 2.2% monthly HPI decrease was the largest August-to-September decline in Ottawa’s series, which dates to 2005. Even after adjusting for normal seasonal patterns, the benchmark declined 1.5%, also the largest September decrease in the series. The result warrants attention, particularly alongside weaker absorption, but one month alone does not establish a sustained price trend. 

There were 2,927 new listings in September, up 3.0% from a year earlier and 38.1% from August. Some increase is normal as the fall market begins, but the median August-to-September increase over the previous 10 years was 12.9%. Looking across July through September, 7,576 homes were newly listed, the highest total for those three months since 2016. Over the same period, sales recorded their third-lowest total. 

Active listings reached 4,813, up 7.9% from September 2025 and 7.1% from August. This was the second-highest September level since 2016. The sales-to-new-listings ratio fell from 47.3% in August to 34.5% in September, meaning roughly one home sold for every three new listings. Months of inventory rose from 4.5 to 4.8. Among September results over the past decade, this year recorded the lowest sales-to-new-listings ratio and highest level of months of inventory. 

For buyers, the increase in availability may provide greater choice, more time to make decisions, and additional negotiating room. Affordability and borrowing costs, however, continue to constrain demand.  

Other transaction measures also pointed to more subdued conditions. Homes sold for an average of 97.5% of their listing price, compared with 98.1% last September, while the median time on market increased from 22 to 27 days. 

Single-family homes recorded 4.4 months of inventory and a benchmark price of $705,100, nearly unchanged from a year earlier but down 3.0% from August. Townhouses recorded 4.0 months of inventory and a benchmark price of $546,500, down 2.2% year over year but essentially unchanged from August. 

Apartment remained the softest of the three major property types. Months of inventory rose from 6.3 to 7.3, while the sales-to-new-listings ratio fell from 43.0% to 27.0%. The apartment benchmark price was $380,800, down 6.1% from a year earlier and 3.1% from August. Although the average apartment sale price increased 0.9% year over year, the benchmark movement suggests that changes in the mix of apartment sales supported the average. Taken together, the September measures indicate that apartment supply continues to build relative to sales. 

Regional Market Comparison 

Ottawa’s three suburban submarkets continued to be the engine of the market, accounting for 734 sales, or 72.7% of citywide activity. Their combined sales total was down 8.0% from 798 in September 2025, with each of the three submarkets recording fewer sales than a year earlier. 

Ottawa Suburb West had the firmest absorption among the seven submarkets, with a sales-to-new-listings ratio of 40.7% and 3.7 months of inventory. Ottawa Suburb East recorded 4.3 months of inventory, while Ottawa Suburb South recorded 4.4. 

More supply-sensitive conditions were evident in Ottawa Centre and the rural markets. Ottawa Centre recorded a sales-to-new-listings ratio of 27.6% and 6.8 months of inventory. Months of inventory also reached 6.5 in Ottawa Rural South, 6.3 in Ottawa Rural East and 5.8 in Ottawa Rural West. 

Price movements varied considerably across the rural areas. With monthly sales ranging from 40 to 88 transactions, large percentage changes in these markets should be interpreted cautiously.  

Looking Ahead 

Through the summer, one of the central questions for Ottawa’s market was not simply how many homes were available, but how quickly that supply was being absorbed. Absorption weakened through August and September. The sales-to-new-listings ratio fell from 52.4% in July to 47.3% in August and 34.5% in September, while months of inventory rose from 3.5 to 4.5 and then 4.8. September sales were nearly unchanged from August, but new listings increased 38.1%, meaning the latest shift came primarily from substantially more supply competing for a similar number of sales. 

How long that imbalance lasts will matter. Listings normally decline as the market moves through October and November, so some improvement in absorption would indicate that September’s surge was partly seasonal. If the sales-to-new-listings ratio remains near its current level, months of inventory remains elevated, and the HPI continues to decline, the evidence of a broader price adjustment would become stronger.  

Apartments remain the clearest pressure point. CMHC also expects Ottawa’s rental market to soften as a large construction pipeline is completed. Most of that new supply is purpose-built rental housing rather than resale condominiums, so it should not be treated as a direct addition to resale inventory. It may nevertheless influence demand as renters and prospective buyers weigh a wider range of housing options. 

External forecasts generally point to limited near-term price growth and a gradual recovery. TD Economics forecasts Ontario’s existing-home prices to average 2.6% lower in 2026, followed by growth of only 0.6% in 2027, while RBC forecasts Canada’s benchmark price index to decline 2.3% in 2026 before edging up 0.8% in 2027.  CMHC’s Ottawa outlook similarly expects sales to stabilize but says slower demand growth and greater supply limiting price increases. 

Some buyers may also be shifting from resale homes to new construction. GOHBA reported 464 new-home sales in Ottawa in August, up 9.7% from July and 55.2% from a year earlier, while year-to-date sales were 50.4% higher. This acceleration coincides with expanded HST relief for qualifying new homes, which may be improving the relative appeal of new construction and drawing some demand away from the resale market. The figures do not establish that the rebate caused the increase, but the contrast between stronger new-home sales and weakening resale absorption is another trend worth monitoring.   

These forecasts cover different geographic areas and use different price measures, so their figures are not directly comparable with Ottawa’s monthly results. Their common direction is nevertheless consistent with the local data: the market is offering buyers more choice, while current supply and demand conditions provide limited support for rapid growth. October and November will provide an important test of whether absorption begins to recover as fall listings ease or whether the softer conditions persist into the end of the year.

(SOURCE: OREB)

Read

OTTAWA REAL ESTATE-AUGUST STATS (2026)

Ottawa Home Sales Pull Back Sharply in August While Prices Hold Steady

Ottawa’s housing market lost momentum in August. Sales declined sharply both year over year and from the previous month, reversing July’s incremental improvement and widening the year-to-date gap compared with 2025.

The slowdown was not driven by a new influx of supply. New listings and active listings both declined from July, but sales fell much faster, weakening the relationship between available supply and demand. Listing activity also suggests that some sellers may be pausing or reassessing their plans, rather than proceeding under current conditions. Months of inventory rose to its highest August level since 2016.

Pricing remained comparatively stable. The average sale price and composite benchmark price were both slightly higher than a year earlier, while the median price declined modestly. Overall, August presents a softer picture heading into the fall market, with mixed indicators of market strength and weakness.

“Prices remained relatively steady despite the pullback in sales, which tells us this is not a simple story of the market moving uniformly in one direction,” said OREB President Tami Eades. “Buyers are seeing less competitive conditions and have more time to make decisions, while sellers are facing more competition and may need to be thoughtful about pricing and positioning their homes for the current market. One month does not establish a trend, but the shift in sales and inventory is something we’ll be watching closely as we head into the fall market.”

Residential Market Activity

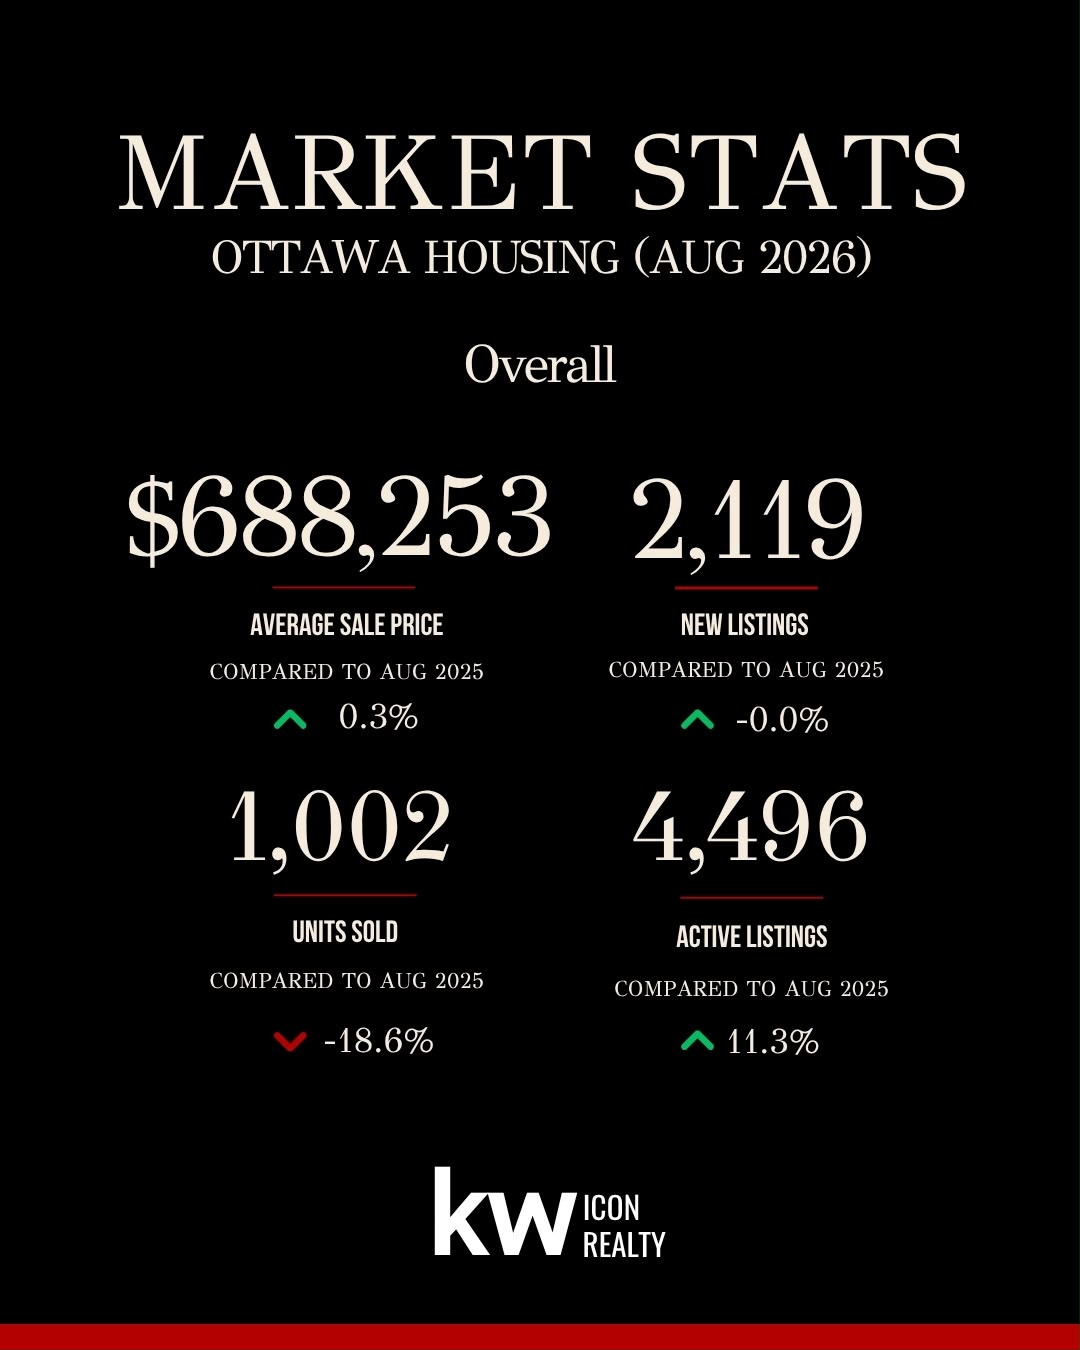
A total of 1,002 homes were sold through the MLS® System in August, down 18.6% from August 2025. Sales also declined 24.4% from July. By comparison, the median July-to-August decline over the previous 10 years was 5.8%, confirming that this year’s slowdown was substantially larger than normal seasonal variation. The August total tied 2022 for the lowest August sales count since 2016.

The sales decline extended across all three major property types:

  • Single-family sales fell 16.3% year over year to 535 transactions.

  • Townhouse sales fell 19.9% to 310.

  • Apartment sales fell 22.3% to 136.

This broad-based weakness differs from earlier months, when the softer activity was more concentrated in townhouses and apartments.

Year to date, 9,283 homes have sold in Ottawa, down 6.9% from the same period in 2025. The year-to-date shortfall widened from 5.2% at the end of July, reversing the incremental improvement recorded last month. Total year-to-date dollar volume was approximately $6.5 billion, down 7.2% year over year.

Prices and Market Balance

The average residential sale price was $688,253 in August, up 0.3% from a year earlier and 0.7% from July. The median price was $622,357, down 1.2% year over year and 2.0% from July.

The MLS® Home Price Index, a measure less affected by changes in the types of properties sold, recorded a composite benchmark price of $637,700. This was 1.0% higher than in August 2025 and 0.6% higher than in July. Taken together, the price measures indicate that values were considerably steadier than sales activity.

There were 2,119 new listings in August, unchanged from a year earlier and down 16.2% from July. Active listings totalled 4,496, up 11.3% year over year but down 3.9% from July. The monthly declines in new and active listings were broadly consistent with seasonal patterns, but active inventory remained at its highest August level since 2016.

The decline in active listings should not be interpreted as inventory being absorbed primarily through sales. An OREB review of listing records indicates that terminations, cancellations and expirations became more prominent relative to completed transactions through the summer. Although these non-sale removals declined from July, sales fell more sharply, meaning a greater proportion of properties left the market without producing a sale. One explanation for this behaviour could be that some sellers may be stepping back or reassessing their plans to sell under current conditions.

The sales-to-new-listings ratio fell from 52.4% in July to 47.3% in August as sales declined faster than new listings. Months of inventory increased from 3.5 to 4.5. Over the previous 10 years, the median July-to-August change in months of inventory was zero, and no increase exceeded 0.4 months. This year’s one-month jump in MOI therefore represents a meaningful weakening in absorption rather than a typical summer movement.

Other transaction measures changed only modestly. Homes sold for an average of 97.9% of their listing price, unchanged from August 2025, while the median time on market increased from 28 days last August to 29 days. These figures remain consistent with broadly balanced conditions, despite the softening of other indicators.

Single-family homes remained the most stable major segment. The single-family benchmark price rose 2.2% year over year, while months of inventory reached 4.0. Townhouses recorded 4.1 months of inventory, with active listings 27.1% above last year and a benchmark price 4.0% lower year over year. The weakening of the townhouse market is something worth monitoring closely.

Of all the property segments, apartment conditions remained the softest in August, continuing the pattern observed throughout 2026 and the second half of 2025. Apartments recorded 6.3 months of inventory, a 43.0% sales-to-new-listings ratio and a median of 42 days on market. However, active apartment listings declined from July, the sales-to-new-listings ratio improved slightly and the apartment benchmark rose 1.9% month over month. The August figures therefore show continued softness, but not a decisive new deterioration.

Regional Market Comparison

Ottawa’s three suburban submarkets continued to account for more than 70% of residential sales in August, but all three recorded year-over-year declines. Sales fell 14.3% in Ottawa Suburb West, 20.0% in Ottawa Suburb East and 25.1% in Ottawa Suburb South.

Ottawa Suburb West had the firmest absorption among the three suburban markets, with a sales-to-new-listings ratio of 51.9% and 3.6 months of inventory. Ottawa Suburb East and Ottawa Suburb South each recorded 4.1 months of inventory, with sales-to-new-listings ratios below the citywide level.

Softer conditions were more pronounced in Ottawa Center and Ottawa Rural East. Ottawa Center recorded 81 sales, a sales-to-new-listings ratio of 38.2% and 7.0 months of inventory. Ottawa Rural East recorded 84 sales, a ratio of 40.6% and 6.5 months of inventory.

Ottawa Rural West was the only submarket to record a year-over-year sales increase, rising 22.6%, and had the highest sales-to-new-listings ratio at 62.3%. However, its 76 transactions represented a relatively small share of citywide activity, and the percentage increase should therefore be interpreted cautiously.

Overall, the regional results indicate that August’s slowdown was not confined to one part of Ottawa. Absorption remained comparatively firmer in the western suburban and rural markets, while central Ottawa and Rural East experienced more supply-sensitive conditions.

Looking Ahead

August’s softer housing results came against an uncertain, though improving national economic backdrop. Statistics Canada reported that real GDP grew at an annualized rate of 3.3% in the second quarter, while first-quarter growth was revised upward to 0.3%. The Bank of Canada’s July outlook similarly described the economy as showing signs of improvement, while emphasizing that uncertainty remained elevated.

CMHC’s 2026 outlook expects sales in the Ottawa metropolitan area to stabilize, while slower demand growth and increasing supply limit price increases. CMHC also expects the local rental market to continue softening as elevated construction moves toward completion.

At the national level, RBC Economics expects home resales and benchmark prices to decline overall in 2026 before beginning a modest recovery in 2027. Its latest outlook forecasts national transactions rising 6.7% next year, but cautions that the recovery is likely to remain irregular as affordability pressures, slower population growth and economic uncertainty continue to affect demand.

For Ottawa, the central question heading into the fall market is whether August represents a temporary interruption or the beginning of a more sustained slowdown. One month does not establish a trend, but the unusually sharp sales decline, lower sales-to-new-listings ratio, higher months of inventory and wider year-to-date shortfall are important signals to monitor. Whether properties that left the market without selling return during the fall, perhaps with new pricing strategies, will also help indicate whether some sellers were temporarily pausing their plans or withdrawing for a longer period.

(SOURCE: OREB)

Read

OTTAWA REAL ESTATE-JULY STATS (2026)

Ottawa Home Sales Hold Steady as New Listings Ease in July

Ottawa’s housing market held up better than usual as the spring market gave way to summer. Sales in July were virtually unchanged from a year earlier, while new listings edged lower, improving the balance between incoming supply and sales compared with June. July marked the second time in three months that new listings fell below year-earlier levels, adding to signs that the flow of new supply is beginning to moderate and balance, even as the overall number of homes available remained high relative to recent historical trends.

Sales declined 12.7% from June, compared with a median June-to-July decrease of 20.7% over the previous decade. New listings fell at a more typical seasonal pace, allowing the relationship between new supply and sales to improve.

Pricing indicators were mixed, but once again they collectively pointed to stability rather than a market-wide shift. The average sale price was 1.6% lower than in July 2025, while the median price was unchanged. This divergence suggests that the mix of homes sold contributed to the decline in the average price.

Conditions also remained segmented geographically and by type. Absorption was generally firmer in the suburban markets, while the condominium apartment market continued to experience softer conditions, particularly in the downtown core.

“July’s results point to a steady market as it moves through the typical summer slowdown,” said OREB President Tami Eades. “Sales remained close to last year’s level, while fewer new listings helped improve the balance between supply and demand. However, conditions continue to vary significantly by property type and neighbourhood, reinforcing the importance of local data and informed guidance when making real estate decisions.”

Residential Market Activity

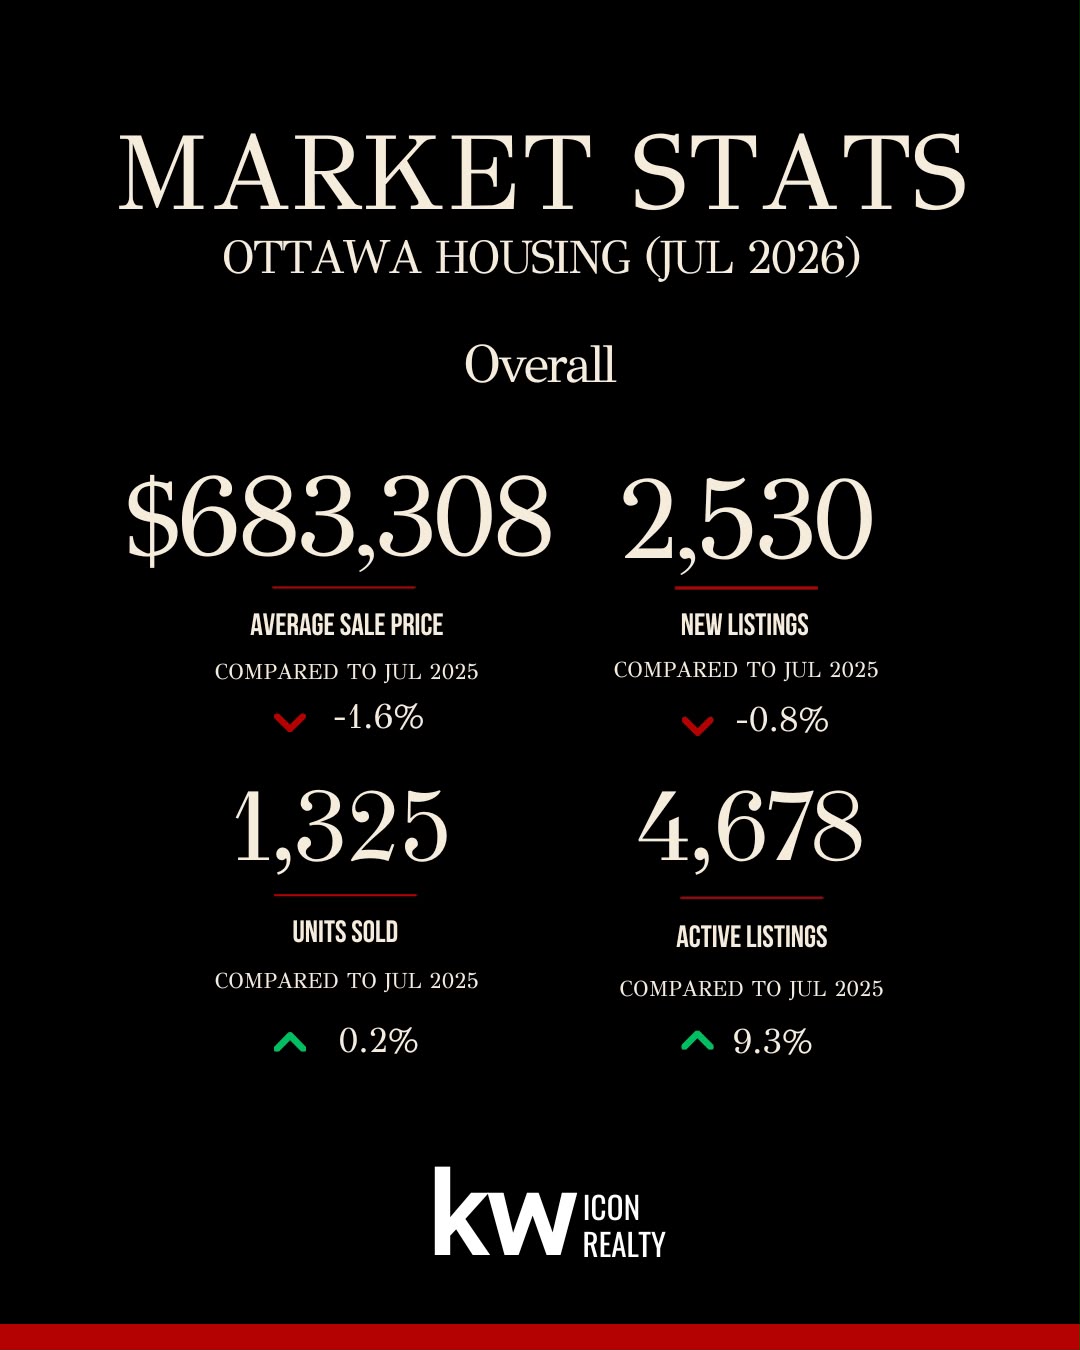
A total of 1,325 homes were sold in the Ottawa area through the MLS® System in July, an increase of 0.2% from July 2025. Although sales declined from June as the spring market gave way to summer, Ottawa retained considerably more of its spring activity than it typically has during recent June-to-July transitions.

Activity continued to vary by property type. Single-family sales rose 5.0% year-over-year to 714 transactions. Townhouse sales declined 4.1% to 417, while apartment sales declined 6.6% to 169. While Townhome and apartment sales both declined compared to 2025, that decline was once again less than the year earlier figures from June.

Year-to-date, 8,288 homes have sold in Ottawa, down 5.2% from the same period in 2025. This July result narrows the year-to-date gap from 6.1% at the end of June. Total year-to-date dollar volume was approximately $5.8 billion, down 5.6% year-over-year.

Prices and Market Balance

The average residential sale price was $683,308 in July, down 1.6% from a year earlier. The median price was unchanged at $635,000.

Taken together with other pricing measures, these figures suggest prices remained broadly stable year-over-year, and that changes in the mix of properties sold influenced the lower average. The MLS® Home Price Index, which is designed in part to adjust for changes in the mix of homes sold, recorded a composite benchmark price of $634,000, down 0.5% year-over-year but up 0.3% from June.

There were 2,530 new listings in July, down 0.8% from a year earlier. Active listings totaled 4,678, up 9.3% year-over-year but down 6.1% from June. Inventory therefore remained high compared with recent historical trends, but the growth in available supply continued to moderate.

The sales-to-new-listings ratio increased from 48.8% in June to 52.4% in July as sales held up comparatively well and fewer new properties entered the market. Months of inventory rose modestly from 3.3 in June to 3.5 in July. Although an increase is typical between June and July, this year’s 0.2-month rise was less than half the median increase recorded over the previous decade.

Other transaction measures were somewhat softer. Homes sold for an average of 97.8% of their listing price, compared with 98.0% in July 2025, while the median time on market increased from 24 to 28 days. July therefore showed improved absorption of incoming listings, but not a broad shift toward tighter market conditions.

Single-family homes remained the steadiest major segment. Months of inventory rose to 3.2, while the single-family benchmark price increased 0.6% year-over-year. Townhouses recorded 3.0 months of inventory, down from June, while the sales-to-new-listings ratio improved to 55.9%. However, the townhouse benchmark price remained 5.1% below last year. The condominium apartment market continued a yearlong trend of having the softest conditions, particularly in downtown Ottawa. Apartments recorded 5.4 months of inventory, a 41.0% sales-to-new-listings ratio and a median of 41 days on market. The apartment benchmark price was down 5.2% year-over-year.

Regional Market Comparison

In July, Ottawa’s suburban markets continued to account for most residential activity, representing more than 70% of all sales. Ottawa Suburb South stood out, with sales rising 8.0% year-over-year while new listings declined 6.6%. Its sales-to-new-listings ratio increased to 55.7%.

Ottawa Suburb West recorded the firmest absorption among the three suburban submarkets, with a sales-to-new-listings ratio of 56.2% and 3.0 months of inventory. Ottawa Suburb East also remained within balanced conditions, with a 54.3% ratio and 3.0 months of inventory.

Conditions remained softer in Ottawa Center. Sales declined 8.3% year-over-year, the sales-to-new-listings ratio was 39.6%, and months of inventory reached 5.6.

Rural results were more variable. Sales increased in Ottawa Rural South and Ottawa Rural West but declined in Ottawa Rural East. These percentage movements should be interpreted cautiously because the smaller number of transactions in rural submarkets means relatively few sales can produce substantial monthly or annual swings.

Overall, the regional data reinforces a market divided by geography as well as property type, with generally firmer suburban absorption and more supply-sensitive conditions in downtown Ottawa. These differences underscore the importance of local market knowledge and a well-prepared comparative market analysis, as citywide figures may not reflect the conditions affecting a particular neighbourhood or property type.

Looking Ahead

Spring concerns about a recession have given way to a more nuanced economic outlook. Statistics Canada reported that real GDP grew 0.3% in May, while the Bank of Canada said in July that there were clear signs economic growth had resumed during the second quarter. Growth remains modest and uncertainty remains elevated, but the backdrop heading into the fall is steadier than it appeared earlier in the year.

The Bank of Canada also held its policy rate at 2.25% in July. While national economic results should not be treated as a direct explanation for Ottawa’s July housing activity, continued growth and stable interest rates provide a more supportive backdrop for housing demand.

In June, the pace of new listings, the direction of inventory and the relative softness of the apartment market were identified as important indicators to watch. One month later, new listings have eased, active inventory has declined from its June level and the sales-to-new-listings ratio has improved. Apartment conditions, however, remain comparatively soft. The key question heading into the fall will be whether the improvement in citywide absorption continues once the market moves beyond the typical summer slowdown.

(SOURCE: OREB)

Read

OTTAWA REAL ESTATE-JUNE STATS (2026)

Ottawa Market Remains Balanced as Supply Shapes June Conditions

Ottawa’s housing market remained balanced in June, with activity easing in line with typical early-summer patterns, though trailing slightly behind 2025 activity levels. Supply remains elevated by recent years’ standards, continuing to give buyers more choice.

The impact of the elevated inventory is presenting differently by property type: single-family homes remained comparatively steady, townhomes showed more volatility, and apartment-style properties continue to be the softest segment.

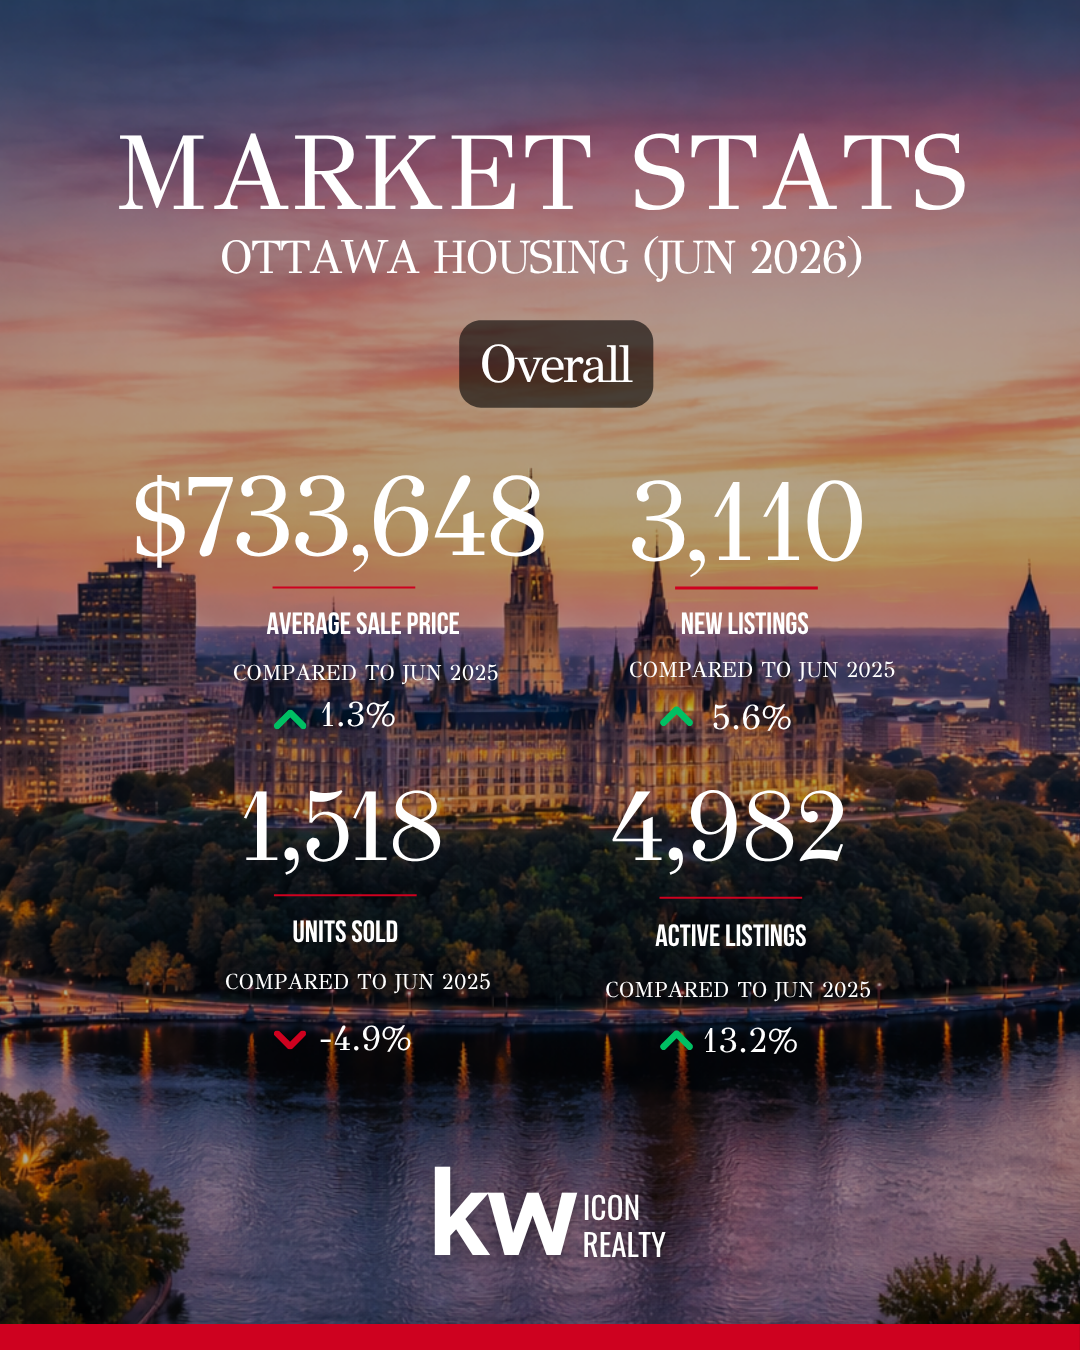
Pricing reflected that mixed picture. The average residential sale price was $733,648 in June, up 1.3% from a year earlier, while the median price was $655,000, down 1.3%.

The market continues to unfold against a cautious economic backdrop, though economic indicators are less gloomy than last month leading to some guarded optimism. The Bank of Canada held its policy rate in June, and Statistics Canada reported that real GDP grew in April after contracting in March. At the same time, uncertainty around North American trade policy continues to weigh on the broader economic outlook.

Overall, June showed a market that remains steady but is more divided beneath the surface. Supply is shaping conditions, but not overwhelming them, and the next phase of the market will depend on how well demand continues to absorb available listings across different property types.

“As we move through the summer market, the key story isn’t simply higher inventory, it’s how well demand continues to absorb that supply,” said OREB President Tami Eades. “Ottawa remains a fundamentally balanced market, but we’re seeing clear differences emerge between property types and neighbourhoods. That’s why buyers and sellers should focus less on citywide headlines and more on local market conditions. Working with a REALTOR® who understands those micro-market dynamics is more valuable than ever.”

Residential Market Activity

In June, 1,518 homes were sold through the MLS® System in Ottawa, a 4.9% decrease compared to June 2025. While sales were lower than May’s 1,616, that decline is consistent with the normal transition from the spring market into the early-summer period.

Sales activity varied by property type. Single-family homes continued to account for the largest share of activity, with 879 sales in June, down 1.8% from a year earlier. Townhouse sales totalled 429, down 7.3%, while apartment-style properties recorded 178 sales, down 14.0%.

This reinforces the property-type divide that has been building through the first half of the year: single-family demand has been steadier, while townhomes and especially apartments have carried more of the market softness.

Year to date, 6,969 homes have sold in Ottawa, down 6.1% from the same period in 2025. Total dollar volume was $4.9 billion, down 6.2% year over year. The year-to-date figures point to a market that remains active, but still below last year’s sales pace as the first half of 2026 comes to a close.

Prices and Market Balance

June’s price story was about how supply is being absorbed across different parts of the market. The average price was higher than a year ago, while the median price and benchmark measures were softer, suggesting that property mix continued to influence the headline numbers.

New listings were up year over year, active listings continued to rise, and the sales-to-new-listings ratio settled at 48.8%. Months of inventory reached 3.3, up from 2.8 last June. These figures remain consistent with balanced-market conditions.

Importantly, the additional supply has not translated into a broad weakening in transaction conditions. The sale-to-list price ratio remained at 98.5%, unchanged from June 2025, while the median days on market rose only modestly from 19 to 22 days. That suggests Ottawa is seeing more pricing discipline, not a complete shift in market conditions.

The property-type split is the clearest market-balance signal. Single-family homes remained the most stable segment, with 2.8 months of inventory and the strongest sale-to-list ratio among the major property types.

Townhomes continued to adjust as listings accumulated, with active inventory up 27.6% from last June and months of inventory rising to 3.2.

Apartment-style properties (condos) remained the softest segment, with 5.3 months of inventory and weaker benchmark pricing than the broader market.

The MLS® Home Price Index, which helps adjust for changes in the mix of homes sold, reinforced this divide. The composite benchmark price was down 1.3% year over year, with single-family down 0.7%, townhomes down 3.9%, and apartments down 6.0%.

Overall, June does not point to a market-wide price correction. It points to a balanced market where elevated supply is creating more pricing pressure, and where the clearest signs of high-supply effects remain concentrated in townhomes and apartment-style properties rather than across Ottawa as a whole.

Regional Market Comparison

Ottawa’s regional data reinforced the broader theme of a balanced but uneven market. The three suburban submarkets continued to account for most of the city’s sales activity, led by Ottawa Suburb South with 382 sales, Ottawa Suburb West with 373, and Ottawa Suburb East with 328. Together, those three areas represented more than 70% of Ottawa’s June sales.

The suburban picture was not uniform. Ottawa Suburb South recorded the highest sales total, but Ottawa Suburb West showed the firmest absorption, with the highest sales-to-new-listings ratio among the seven submarkets and the lowest months of inventory.

Ottawa Suburb East remained active, though sales were lower than last year and new listings were up, pointing to more choice for buyers.

Central and rural markets were more uneven. Ottawa Centre recorded 143 sales and had higher months of inventory than the citywide level, while Ottawa Rural East was the only submarket to post year-over-year sales growth. Rural West and Rural South had smaller transaction totals, which makes monthly movements more variable, but both continued to show more supply-sensitive conditions.

Overall, the regional data points to a market shaped by local differences rather than one broad trend. Suburban areas continue to drive most activity, but absorption, supply, and pricing conditions vary meaningfully by area.

Looking Ahead

As Ottawa moves through the summer market, the most useful signals will come less from any single month of sales and more from whether demand continues to absorb elevated supply at a steady pace. REALTORS® should be watching the sales-to-new-listings ratio, months of inventory by property type, median days on market, and whether price trends continue to diverge between single-family, townhouse, and apartment-style properties.

CMHC’s latest data adds important context to the supply story. Ottawa had 17,212 housing units under construction in May,with nearly 14,000 of those apartment units. Combined with national demographic data pointing to slower population growth and fewer non-permanent residents, there remains the possibility of an influx of apartment-style units into the market in a way that could significantly impact market conditions.

While this does not point to an immediate oversupply issue as completed and unabsorbed apartment inventory remains low with 37 apartment units reported in May; it does suggest future pressure will depend less on construction activity itself and more on whether demand continues to keep pace as projects are completed.

The rental side should also be monitored carefully. CMHC reported a 3.0% primary rental vacancy rate in Ottawa in 2025, while the condominium rental vacancy rate was much tighter at 0.6%. That means the apartment outlook is not simply a story of excess supply. It is a question of how resale demand, rental demand, investor activity, and new apartment completions interact over time.

REALTORS® in Ottawa, as always, would do well to thoroughly understand the micro-market they are operating in for their clients.

(SOURCE: OREB)

Read

OTTAWA REAL ESTATE-MAY STATS (2026)

Seasonal Activity Improves, but Ottawa’s May Market Remains Cautious

Ottawa’s housing market remained balanced in May, with activity improving from April but continuing to trail last year’s spring pace. A total of 1,616 homes sold in May, up from 1,336 in April, reflecting the typical lift as the spring market progressed. However, sales were down 10.6% compared to May 2025. These slower sales are becoming a theme thus far in 2026, even as the market remains active.

The sales-to-new-listings ratio rose to 48.2%, while months of inventory eased to 3.0, indicating demand kept better pace with new supply than it did in April. Active listings remained elevated at 4,917, keeping pressure on sellers to price strategically.

Average prices across market segments were mixed, though overall pricing remained relatively stable. Single-family home pricing was flat year over year, while average prices for townhomes and apartments saw modest declines. Overall pricing was less than one percentage point below last year’s level, indicating continued market stability. The average residential sale price was $721,270 in May, up from $712,184 in April, and relatively flat at 0.9% below May 2025. The median sale price followed a similar pattern, rising to $660,000 from $650,000 in April while remaining 1.6% lower than last May.

Performance varied by property type. Single-family homes remained resilient, with average prices essentially unchanged year over year and the median price up 1.3%. Townhomes and apartment-style properties continued to face softer conditions, with both average and median prices below last year’s levels.

The MLS® Home Price Index (HPI) composite benchmark price increased 0.9% from April but remained 0.6% below May 2025, reflecting continued variation across market segments.

Economic uncertainty continues to influence market activity. Recent GDP data has fueled discussion about Canada’s economic momentum, while the Bank of Canada has continued to take a cautious approach to interest rates. CMHC data reported lower employment levels in the first quarter compared to a year earlier, while CREA’s labour-market charts point to stronger full-time job growth and an unemployment rate that has eased from its early-2026 peak.

Ottawa’s market remains balanced, but the data also points to clear challenges. Sales continue to lag last year’s pace, inventory is elevated, and softer segments are weighing on the broader price picture. The strength of the summer market will depend on whether demand continues to absorb supply at a steady pace.

“The Ottawa market is not moving in one direction across all property types,” says OREB President Tami Eades. “May brought the seasonal increase in activity we typically expect to see in Ottawa’s housing market, but sales continue to trail last year’s pace. While economic uncertainty continues to influence consumer confidence, the key question moving into the summer market will be whether demand continues to keep pace with supply. The market remains active, but inventory levels, employment trends, and buyer confidence will all play an important role in shaping the months ahead.”

Residential Market Activity

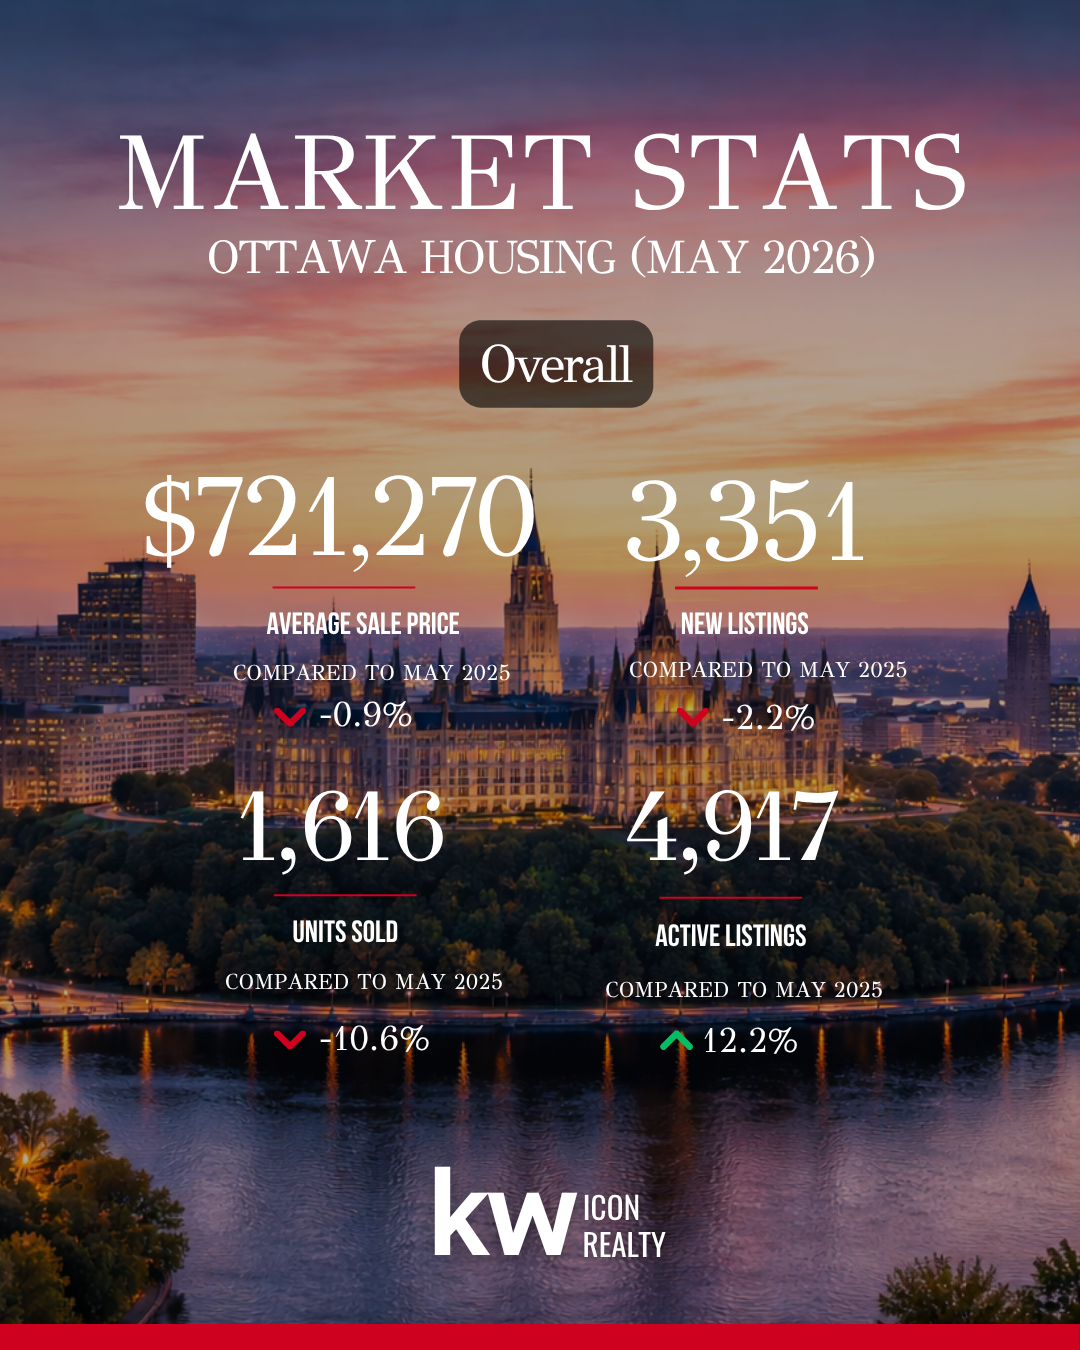
In May, 1,616 homes were sold through the MLS® System in Ottawa, a 10.6% decrease compared to May 2025, but a clear increase from 1,336 sales in April. The month-over-month gain reflects the typical spring lift in activity, even as demand continues to trail last year’s stronger spring pace.

Sales activity was down in May compared to 2025, though the extent of that decline varied by property type. Single-family homes recorded 904 sales in May, down 8.6% from a year earlier. Townhouse sales totalled 481, down 14.3%, while apartment-style properties recorded 203 sales, down 12.1%. The segment-level results point to a market where demand remains present, but activity is trailing 2025 across all segments.

Supply remained elevated. New listings totalled 3,351 in May, down 2.2% from May 2025, while active listings rose to 4,917 units, up 12.2% year over year and above April’s 4,535 listings. While new listings did not surge this month, the elevated level of active inventory shows that supply has continued to accumulate.

The sales-to-new-listings ratio improved to 48.2%, up from 41.0% in April and consistent with balanced market conditions.

Year to date, 5,453 homes have sold in Ottawa, down 6.3% from the same period in 2025. New listings total 12,284, up 5.4%, while average active listings are up 14.8%. The year-to-date sales-to-new-listings ratio of 44.4% and 3.5 months of inventory point to a market that remains balanced overall, but one where sellers face more competition than they did last spring.

Prices and Market Balance

Price trends remained stable in May, but they were not uniform across property types. The average residential sale price in May was $721,270, down 0.9% from May 2025 but up from $712,184 in April. The median price was $660,000, down 1.6% year over year and up from $650,000 in April. Year to date, the average price is $694,539, down 0.6%, while the median price is $639,000, down 1.7%.

Single-family homes remained the most resilient segment, with an HPI benchmark price of $723,800, up 0.9% from April and 0.3% year over year. The average single-family sale price was essentially unchanged from last May, while the median price rose 1.3% to $800,000.

The townhome segment softened in May data compared to recent months. Earlier in the year, townhome activity was holding up comparatively well, but May reversed that pattern. Townhouse sales fell 14.3% year over year, pulling year-to-date sales 2.8% below 2025. Pricing has not fallen sharply month over month, with the townhouse HPI benchmark at $557,500, down 0.4% from April and 3.2% from last May. The larger signal is softer absorption, as active listings remain elevated and months of inventory sit well above last year’s level.

Apartment-style properties continued to show the most pronounced pressure. The apartment benchmark price was $385,500, up 1.5% from April but down 6.7% from May 2025. Average and median apartment prices were also lower year over year. This weakness is not unique to Ottawa; Toronto’s condo sector has also been affected by weaker investor demand and higher carrying costs. Ottawa’s apartment segment, however, should still be understood within local conditions: the data points to a slower, more price-sensitive segment, not a broad market correction.

Months of Inventory:

  • Single-Family: 2.7

  • Townhome: 2.7

  • Apartment: 4.8

Ottawa is not experiencing broad-based price growth, but neither is the market showing a uniform decline in price. Single-family homes continue to provide support, townhomes are adjusting, and apartment-style properties remain the softest part of the market. For sellers, accurate pricing remains critical; for buyers, the data points to a market where patience and property-specific analysis matter more than broad assumptions about Ottawa as a whole.

Regional Market Comparison

Ottawa’s regional picture was uneven in May, reinforcing that the citywide market is not moving as one single market. The central market and Ottawa Rural West were the only subareas to record year-over-year sales gains, while the suburban areas continued to drive most of the overall activity.

Ottawa Centre had the clearest positive activity signal, with sales up 13.5% from May 2025 and prices also higher year over year. This suggests stronger engagement in the central market after a softer start to the year, though the area’s varied property mix means monthly price movements should be interpreted with some caution.

The suburban markets remained the core of Ottawa’s sales activity, but the story differed by area. Ottawa Suburb West recorded the highest sales total and the lowest months of inventory, pointing to relatively stronger absorption. However, prices were lower than last May, so its strength was more about activity than price growth. Ottawa Suburb South remained steady but softer than last year, while Ottawa Suburb East saw a sharper decline in sales even as prices moved higher.

Rural markets were more variable, which is typical given smaller transaction volumes. Ottawa Rural West was the relative bright spot, with sales slightly above last May, while Ottawa Rural East and Rural South both recorded weaker activity. Rural East also had the highest inventory level among the subareas, pointing to slower absorption.

Overall, the regional data points to a market shaped by local differences rather than one broad trend. Central Ottawa improved in May, the west remained active, and rural conditions were more uneven. For buyers and sellers, neighbourhood, property type, and local competition continue to matter more than the citywide averages alone. Detailed regional tables are available in the non-HPI report included in the monthly stats package.

Looking Ahead

As Ottawa moves into the summer market, the most useful signals will come less from broad forecasts and more from whether demand continues to absorb supply at a steady pace. REALTORS® should be watching the sales-to-new-listings ratio, months of inventory by property type, median days on market, sale-to-list ratios, and whether benchmark prices continue to diverge between single-family, townhouse, and apartment-style properties.

CMHC’s latest construction data adds important context. Housing starts were lower year over year across all dwelling types in April, but the pipeline is shifting in composition. Rental projects accounted for 61% of starts by market type, while apartments made up most new starts and the large majority of units currently under construction. That changing mix will matter most for apartment-style resale pricing, investor demand, and rental-market competition as projects move toward completion.

Completed and unabsorbed inventory should also be monitored closely. CMHC’s April data shows this inventory has risen, with the largest concentration in row and single-detached homes. For REALTORS®, absorption of newly completed units will be an important companion indicator to resale inventory, especially in segments where pricing has already become more sensitive.

Taken together, the indicators to watch are clear: resale inventory, new listings, absorption of completed new homes, the apartment-heavy construction pipeline, and local employment conditions. These will offer a better read on Ottawa’s next phase than any single month of sales or pricing data alone.

(SOURCE: OREB)

Read

OTTAWA REAL ESTATE - APRIL STATS (2025)

Momentum Builds in Ottawa’s Housing Market Amid Greater Certainty

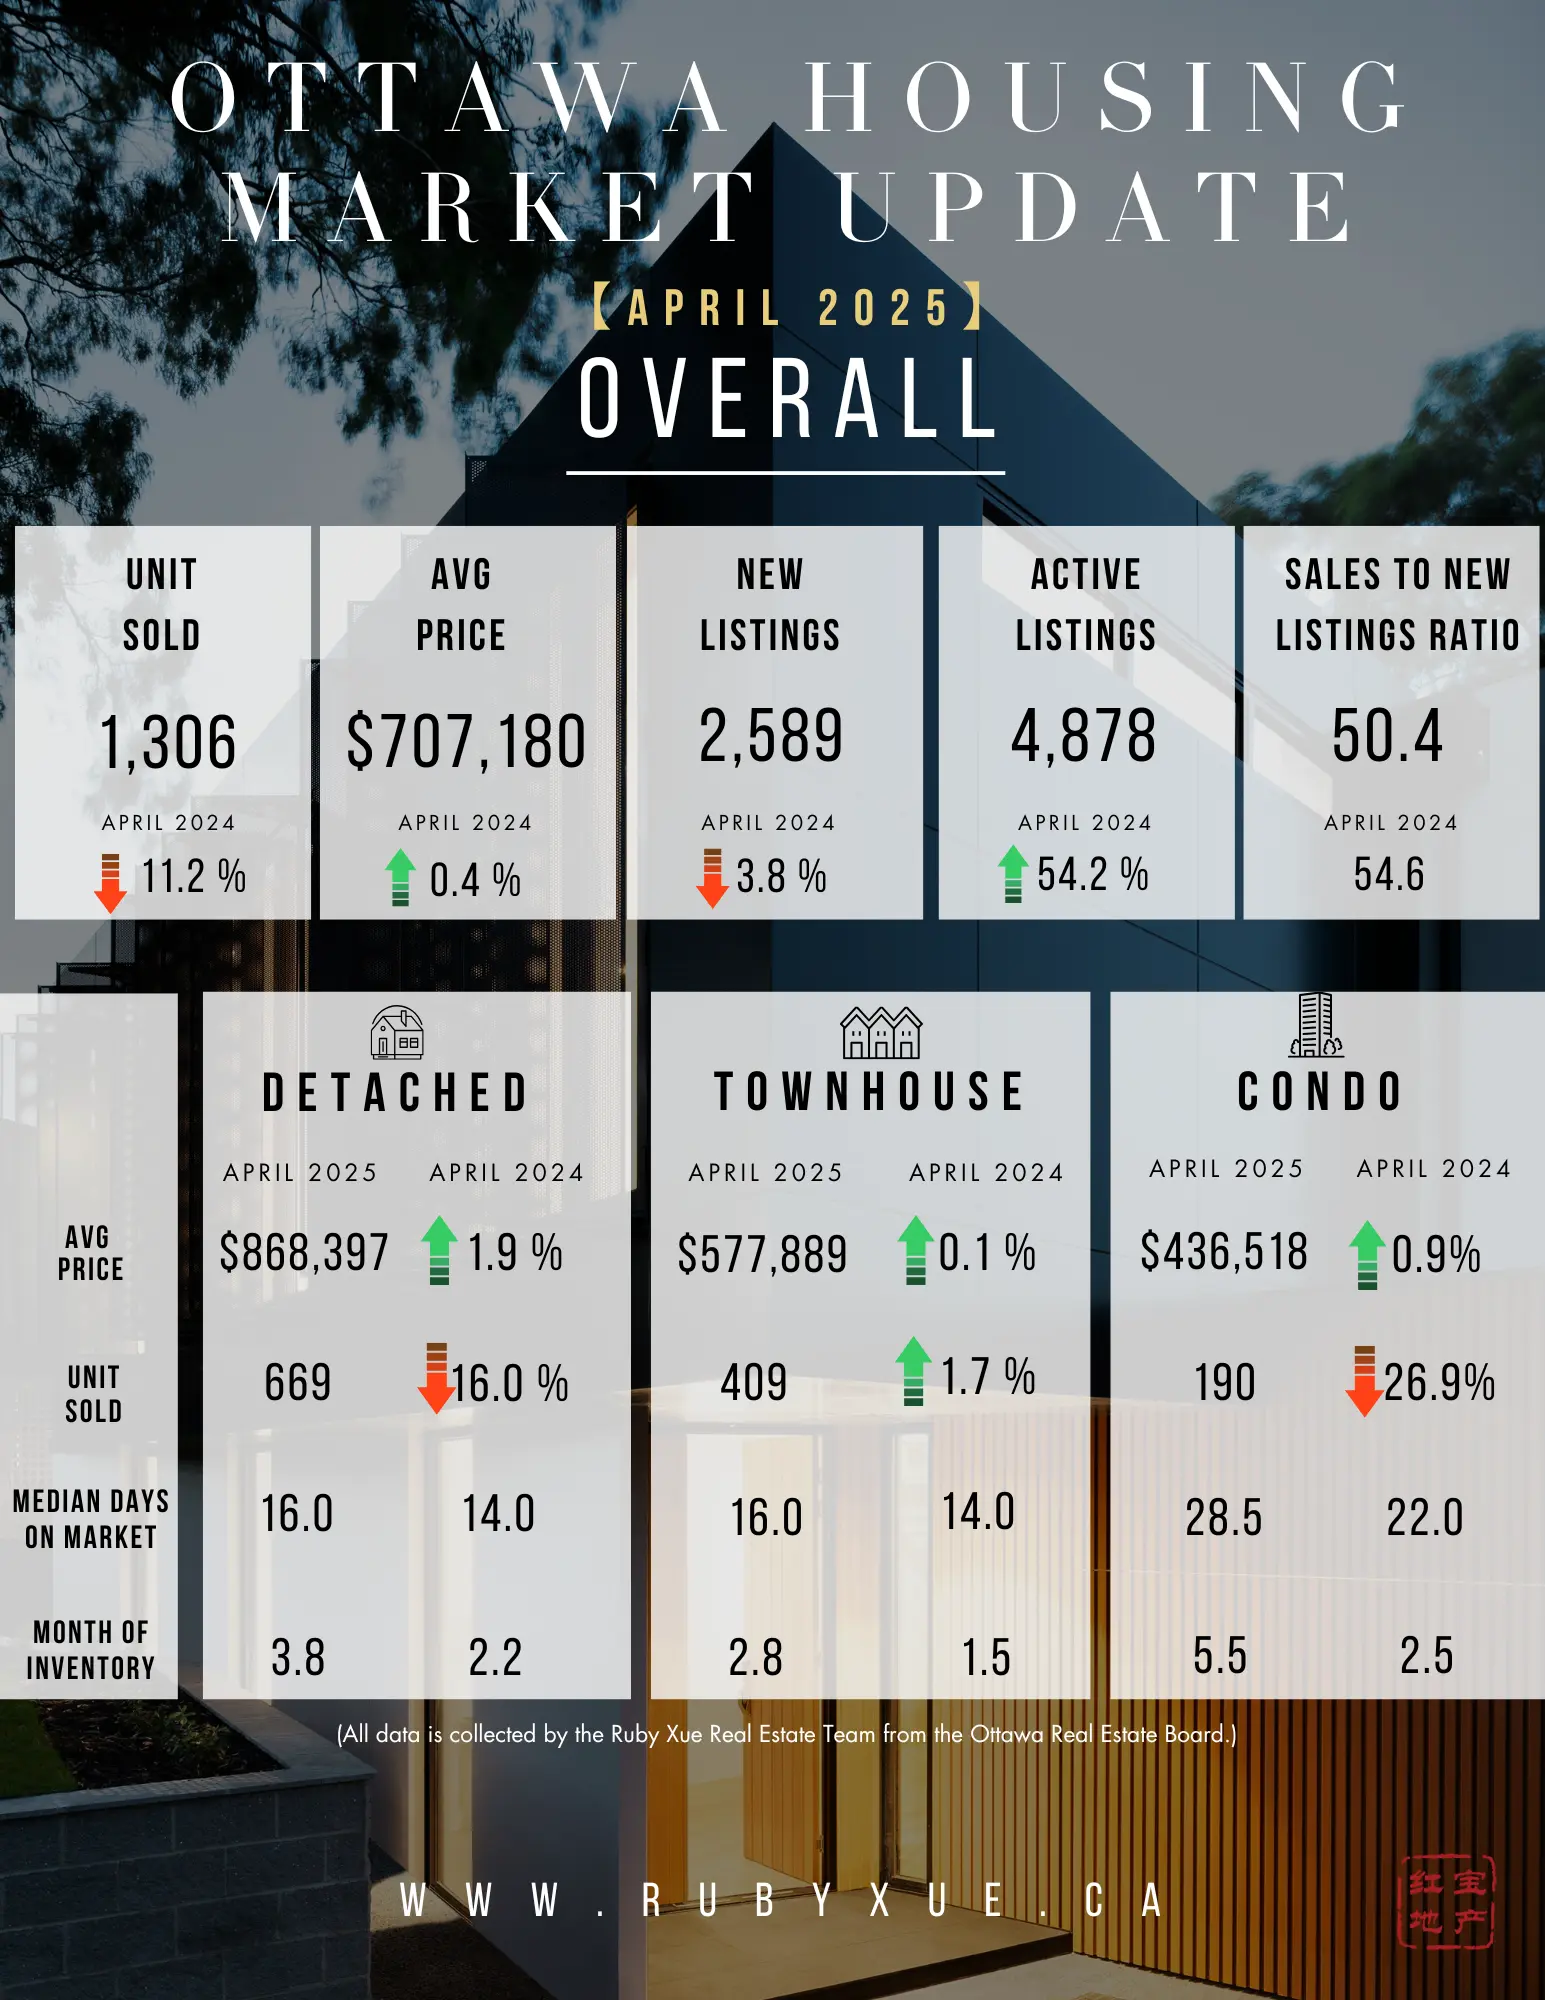
The number of homes sold through the MLS® System of the Ottawa Real Estate Board (OREB) totaled 1,306 units in April 2025. This represented an 18.4% increase from March 2025, but an 11.2% decline from April 2024.

Home sales were 17.6% below the five-year average and 16.2% below the 10-year average for the month of April.

“While April sales were down year-over-year, we saw a healthy month-over-month increase—an encouraging sign of growing momentum as we move through the spring market,” says OREB President Paul Czan. “Inventory remains at higher levels compared to previous years, indicating a gradual move towards a balanced market.”

“With more certainty following the federal election, buyers are returning with greater confidence—but they’re proceeding cautiously, taking their time, including conditions in their offers, and being more selective,” adds Czan. “Sellers, meanwhile, are adjusting to longer days on market, which makes strategic pricing and thoughtful home preparation more important than ever. If the listing is priced well, shows well, it’s moving—possibly getting multiple offers. Looking ahead, we’ll be watching how the federal government’s recent housing commitments translate into action. Policies aimed at increasing supply, improving affordability, and supporting first-time buyers are welcome steps toward meaningful impact here in Ottawa.”

By the Numbers – Prices:

  • The overall MLS® HPI composite benchmark price was $631,200 in April 2025, a 1.1% rise compared to April 2024.

    • The benchmark price for single-family homes was $703,200, up 1.0% year-over-year in April.

    • By comparison, the benchmark price for a townhouse/row unit was $440,000, an increase of 4.4% from 2024.

    • The benchmark apartment price was $404,000, a 2.8% decline from the previous year.

  • The average price of homes sold in April 2025 was $707,180, a 0.4% increase from April 2024.

  • The total dollar volume of all home sales in April 2025 amounted to $923.5 million, a 10.8% drop compared to the same period last year.

OREB cautions that the average sale price can be useful in establishing trends over time but should not be used as an indicator that specific properties have increased or decreased in value. The calculation of the average sale price is based on the total dollar volume of all properties sold. Prices will vary from neighbourhood to neighbourhood.

By the Numbers – Inventory & New Listings:

  • The number of new listings declined by 3.8% compared to April 2024, with 2,589 new residential properties added to the market. New listings were 2.8% above the five-year average and 5.6% above the 10-year average for the month of April.

  • Active residential listings totaled 4,878 units at the end of April 2025, reflecting a 54.2% surge from April 2024. Active listings were 86.9% above the five-year average and 51.3% above the 10-year average for the month of April.

  • Months of inventory stood at 3.7 at the end of April 2025, compared to 2.2 in April 2024. The number of months of inventory is the number of months it would take to sell current inventories at the current rate of sales activity.

    (SOURCE: OREB)

Read

What Do These Numbers Mean for You?

Ottawa's most trusted real estate agent

Whether you're a seller trying to pinpoint the perfect list price or a buyer looking for the right opportunity, we can provide the specific insight you need.

This website may only be used by consumers that have a bona fide interest in the purchase, sale, or lease of real estate of the type being offered via the website. The data relating to real estate on this website comes in part from the MLS® Reciprocity program of the PropTx MLS®. The data is deemed reliable but is not guaranteed to be accurate.